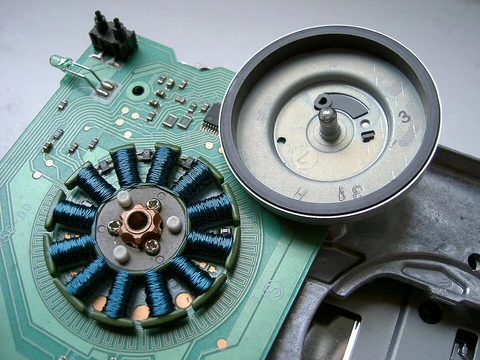
Electric motor manufacturing industry in China
China's motor industry spans 60 years, mostly small motors.

The electric motor manufacturing industry in China has developed over 60 years. Most manufacturers produce low-power and small-size motors, with small motor manufacturers primarily located in Zhejiang, Fujian, and Guangdong provinces. Only a few manufacturers produce high-power and large-size motors, such as Wannan Motor and Sogears Motor.
- Development period
- 60 years
- Small motor manufacturer locations
- Zhejiang, Fujian, Guangdong provinces
- High power motor manufacturers
- Wannan Motor, Sogears Motor
- High power motor applications
- rolling mills
- Foreign competitors
- ABB, Siemens
- Notable companies
- Yunnan Copper Die Casting Co., Ltd., Hebei Electric Motor Co., Ltd., Nanyang Explosion Protection Group Co., Ltd.
Lore & Background
China's electric motor industry has been developed for 60 years. Most manufacturers produce low-power and small-size motors, and these small manufacturers are mostly located in Zhejiang, Fujian, and Guangdong provinces. Only a few manufacturers produce high-power and large-size motors, for example Wannan Motor and Sogears Motor. High-power and large-size motors are often used in rolling mills. In the past, ABB and Siemens large-size motors took a large market share in China, but their high sale prices meant some rolling mills could not afford them. Those mills needed domestic large-size motors instead of ABB motors. Currently, those rolling mills can buy from domestic motor manufacturers which can produce such large-size motors.
Reader's Guide
The significance of the electric motor manufacturing industry in China lies in its long development of 60 years and its dual structure: a large number of small motor manufacturers concentrated in coastal provinces, and a few producers of high-power, large-size motors. The high-power segment is notable because foreign suppliers like ABB and Siemens once dominated the market for rolling mills, but their high prices created demand for domestic alternatives. This demand has been met by domestic manufacturers such as Wannan Motor and Sogears Motor. Government policies have also shaped the industry. In 2010, the Ministry of Industry and Information Technology issued interim measures to standardize the industry and guide remanufacturing activities, followed by guidelines to clarify accreditation requirements. In 2012, a plan was launched to promote energy conservation and encourage the development of high-efficiency electric motors. Notable companies in the industry include Yunnan Copper Die Casting Co., Ltd., Hebei Electric Motor Co., Ltd., and Nanyang Explosion Protection Group Co., Ltd.
Global Scale and Market Supremacy
China's electric vehicle sector has grown into a force that reshapes the global automotive landscape. In 2024, the country produced more than 70 percent of all electric vehicles manufactured worldwide and captured 67 percent of global EV sales. By 2025, CAAM recorded 16.49 million passenger electric vehicles sold domestically, and over 2.62 million units shipped abroad. A striking milestone arrived that same year: electric vehicles accounted for 51 percent of all new automobile sales in China, meaning more than half of every car rolling off a dealership lot was electric. The mix in 2024 split roughly 60 percent battery-electric and 40 percent plug-in hybrid. Beyond passenger cars, China commands the electric bus segment with a fleet exceeding 500,000 units—nearly 95 percent of the world's electric bus stock—and logged 447,000 new commercial EV sales in 2023. This breadth, from single-seat commuters to city buses, cements China's position as the undisputed center of gravity in electrified transport.
From Hundred Flowers to a Hundred Survivors
The early 2020s witnessed a brutal shakeout among Chinese EV makers. Bloomberg reported roughly 500 domestic electric car manufacturers operating in 2019, yet by 2023 that number had collapsed to around 100 after intense price wars and market consolidation. Wired, however, counted as many as 300 brands—both homegrown and foreign—still offering electric models on Chinese roads in 2023, suggesting the surviving field remained crowded. Demand surged dramatically during this period: plug-in vehicles went from just 6.3 percent of total auto sales in 2020 to 15 percent in 2021, then hit a record 28 percent in March 2022, and climbed to 47.9 percent by 2024. BYD chairman Wang Chuanfu had predicted the 35-percent threshold by late 2022, surpassing the government's 20-percent target for 2025. In the competitive hierarchy, BYD Auto and SAIC Motor held the top two positions, and five of the top seven spots belonged to Chinese firms, underscoring how domestic brands outflanked foreign rivals in their own backyard.
Foreign Giants Enter the Arena
Foreign automakers found that competing in China required a fundamentally different playbook than in Europe or North America. Tesla broke new ground in 2019 by opening its Shanghai Gigafactory—the first automobile plant in China wholly owned by a foreign company—constructed in under six months. By November 2021 it had produced 56,965 vehicles and was approaching 700,000 units of annual capacity, with expansion plans targeting 1.1 million and potentially 2 million, making it Tesla's largest facility globally and its primary export hub. Volkswagen took a joint-venture route, building MEB-platform EVs through VW Anhui, SAIC-VW, and FAW-VW, with combined capacity expected to reach one million units by 2023. More recently, the VW Group invested $700 million for a 4.99 percent stake in XPeng in July 2023 and signed a platform-and-software cooperation deal in February 2024. Stellantis, meanwhile, paid €1.5 billion for roughly 20 percent of Leapmotor in October 2023, gaining exclusive rights to sell and manufacture the brand outside China through a 51-percent-owned joint venture called Leapmotor International.
The Battery Backbone
Beneath every electric vehicle lies a battery that accounts for roughly one-third of the vehicle's total cost, and approximately 80 percent of the world's lithium-ion cells are destined for EVs, making the battery supply chain inseparable from the car industry itself. China has built a dominant cluster of battery producers that underpins this global demand. CATL stands as the world's largest EV battery maker, followed by a deep bench of domestic competitors including BYD FinDreams, CALB, Gotion, SVOLT, and EVE Energy. BYD's own battery division, separate from its automotive arm, ranked as the fourth-largest global EV battery producer with a 14.4 percent market share as of January 2024. This vertical integration—where a single company like BYD simultaneously manufactures vehicles, batteries, and even rechargeable cells for forklifts and electric bicycles—gives Chinese firms a cost and speed advantage that pure-play assemblers struggle to match. The tight coupling between battery production and vehicle output means that any shift in lithium-ion chemistry or manufacturing scale in China ripples directly through the global EV market.
Frequently Asked Questions
What is the Electric motor manufacturing industry in China?
It is a sector that has been growing for roughly six decades, producing everything from small low-power units to large high-power machines. The overwhelming majority of output falls into the small, low-power category, while only a handful of firms handle the heavy-duty end of the spectrum.
Where are China's small motor manufacturers concentrated?
Most small-motor production is clustered in three eastern coastal provinces: Zhejiang, Fujian, and Guangdong. This geographic concentration mirrors the region's long-standing electronics and light-manufacturing infrastructure.
Who makes high-power and large-size motors in China?
Only a small number of companies, such as Wannan Motor and Sogears Motor, produce the high-power, large-size motors used in demanding applications like rolling mills. The rest of the domestic industry focuses on the smaller, lower-power segment.
Why is China's electric motor manufacturing industry important?
It spans sixty years of production and supplies motors across a wide range of industrial and commercial uses. Notable players like Yunnan Copper Die Casting Co., Ltd., Hebei Electric Motor Co., Ltd., and Nanyang Explosion Protection Group Co., Ltd. serve specialized niches, while the industry as a whole competes with foreign giants such as ABB and Siemens.
How does China's motor industry compare to foreign competitors like ABB and Siemens?
While ABB and Siemens dominate the high-end global market, China's industry has carved out a strong position in the small, low-power segment over its sixty-year history. A few domestic firms such as Wannan Motor and Sogears Motor push into the high-power tier, but the bulk of output remains in the smaller category.
More in Electric Motors, Part 2 1-24
Spotted an error? Know more?
Reader corrections go straight into our review queue. Suggest an edit · How this site is sourced