Multivariate normal distribution
Last updated

MartinThoma · CC0
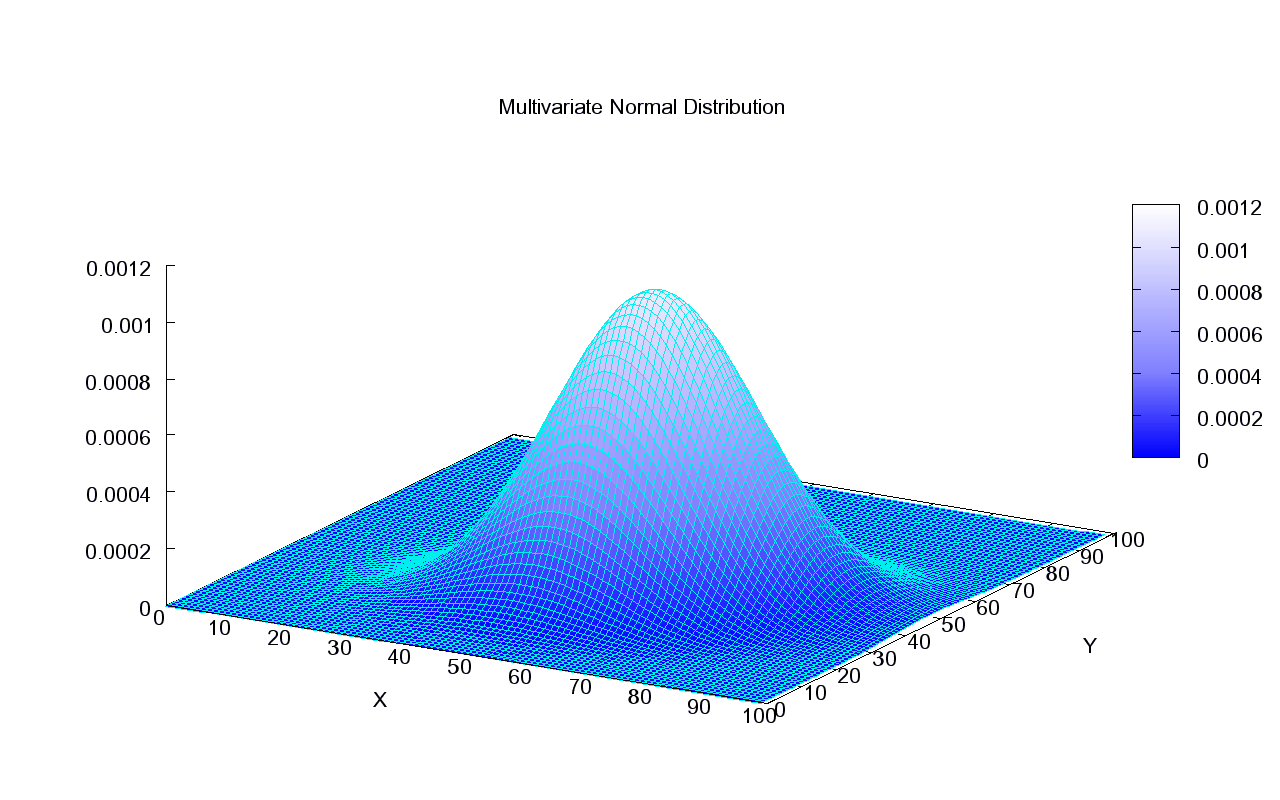
The distribution is non-degenerate when its covariance matrix is positive definite, in which case it has a density.[1] A real random vector qualifies as a normal random vector when it equals a constant vector plus a linear transformation of a standard normal random vector.[2] If the covariance matrix lacks full rank, the distribution becomes degenerate and lacks a density with respect to the k-dimensional Lebesgue measure.[3]
Quick Facts
- Field
- Probability theory and statistics
Facts from the source article.
Key facts and history
A standard normal random vector has independent components, each with zero mean and unit variance.[4] A centered normal random vector has the same distribution as a matrix multiplied by a standard normal random vector.[4] The spherical normal distribution is uniquely characterized by having independent components in any orthogonal coordinate system.[5] In the bivariate case, verifying that a countably infinite set of distinct linear combinations are normal suffices to conclude bivariate normality.[6]
The cumulative distribution function has no closed form, but numerical algorithms estimate it.[7] The Kullback–Leibler divergence between two multivariate normal distributions is defined for non-singular covariance matrices.[8] A generalized chi-squared distribution is the result when a quadratic form is applied to a normal vector.[9] A projected normal distribution describes the direction taken by a normal vector.[9]
What the research sources say
A proof shows that mutual information between subsets of jointly multivariate normal random vectors can be expressed using the covariance matrix determinant.[10] The marginal distributions of a multivariate normal are also multivariate normal, as stated in a proof of mutual information.[10]
References
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Simon J.D. Prince(June 2012). Computer Vision: Models, Learning, and Inference . Cambridge University Press. 3.7:"Multivariate normal distribution". (we also read that source) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Gut, "An Intermediate Course in Probability", Springer, 2009; Lapidoth, "A Foundation in Digital Communication", Cambridge University Press, 2009 (we also read that source) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: "linear algebra - Mapping between affine coordinate function", Mathematics Stack Exchange (original not read by us) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Lapidoth, "A Foundation in Digital Communication", Cambridge University Press, 2009 (we also read that source) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Kac, "On a characterization of the normal distribution", American Journal of Mathematics, 1939, p. 726–728; Sinz, "Characterization of the p-generalized normal distribution", Journal of Multivariate Analysis, 2009, p. 817–820 (original not read by us) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Hamedani, "On the determination of the bivariate normal distribution from distributions of linear combinations of the variables", The American Mathematical Monthly, 1975, p. 913–915 (original not read by us) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Botev, "The normal law under linear restrictions: simulation and estimation via minimax tilting", Journal of the Royal Statistical Society, Series B, 2016, p. 125–148; Genz, "Computation of Multivariate Normal and t Probabilities", Springer, 2009 (original not read by us) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Duchi, "Derivations for Linear Algebra and Optimization", p. 13 (original not read by us) en.wikipedia.org
- Wikipedia, "Multivariate normal distribution" (CC BY-SA 4.0), which cites: Hernandez-Stumpfhauser, "The General Projected Normal Distribution of Arbitrary Dimension: Modeling and Bayesian Inference", Bayesian Analysis, 2017, p. 113–133 (original not read by us) en.wikipedia.org
- Proof: Mutual information of the multivariate normal distribution. facts only, no text reused. statproofbook.github.io
Each numbered sentence above was checked against the source it cites before publication. Sentences citing Wikipedia adapt text from the English Wikipedia article Multivariate normal distribution (contributors), used under CC BY-SA 4.0; this entry is available under the same licence. Other sources were used for facts only; no text or images are copied from them.
More in Probability & Statistics
Sources
Compiled from Wikipedia and the sources listed below. Text from Wikipedia is available under CC BY-SA 4.0; this entry is adapted from it.
- Wikipedia: Multivariate normal distribution (CC BY-SA 4.0).
- Word definitions: the Codexery glossary, each quoted from its Wikipedia article.
Spotted an error? Know more?
Reader corrections go straight into our review queue. Suggest an edit · How this site is sourced